October US inflation to fall after two months of strong rises
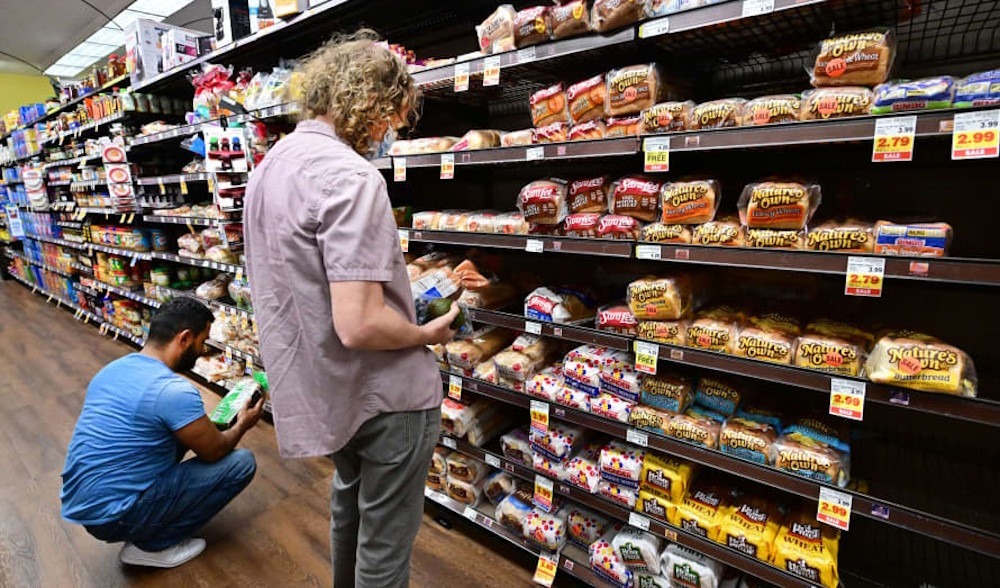
Prices for US goods and services likely increased at a more moderate rate in October following two notably challenging months for American consumers. The consumer price index is anticipated to increase by 0.3% following a 0.6% rise, which marked the most significant increase since April, according to the median projection prior to Tuesday’s Bureau of Labour Statistics’ release. The core measure, which excludes often-volatile energy and food components, likely experienced a cooling effect as well. The survey median experiences a 0.2% increase for October, marking the smallest advance in three months. The agency will refrain from publishing year-over-year figures following its omission of the October 2025 CPI release, which was a consequence of the federal government shutdown that occurred at that time. The October CPI represents the final data point prior to the Federal Reserve’s December meeting, where market participants anticipate an increase in interest rates by policymakers. Economists will meticulously analyse the intricate details of the report for indications regarding inflation risks extending into early 2027.
Economists indicated in a recent note that they expect a constrained transmission of elevated energy costs to the prices of goods, alongside a moderate level of inflation in services. The most recent data on inflation comes on the heels of Friday’s October jobs report, which exceeded expectations. Sustained employment growth has the potential to ensure that consumers continue to spend, while enabling the Fed to maintain its focus firmly on inflation. Another price report, due on Friday, is anticipated to reveal persistent inflationary pressures encountered by companies. The producer price index is anticipated to rise to 6.6% for the year ending in October, marking the most significant annual increase in almost four years. In addition to inflation reports, figures from the National Association of Realtors on Thursday are anticipated to indicate a decrease in contract closings for previously owned homes, reaching the lowest level since 2010, as mortgage rates remain high. In Canada, the manufacturing and wholesale reports for September are anticipated to indicate a deceleration in economic growth for the third quarter.
Manufacturing sales are expected to have increased by a mere 0.1% during that month, a significant decline from the 1.5% growth observed in the previous month. That may be partly attributable to an unforeseen work stoppage at US auto plants, which has negatively impacted cross-border auto trade. Wholesale sales, excluding petroleum, are expected to have experienced a modest increase of 0.5%, following a decline of 1.6% in the previous month. Meanwhile, the Bank of Canada is set to publish a summary of the discussions that culminated in its initial rate increase in three years. In various regions, notable highlights include inflation data from China to Norway, central bank minutes from Japan to Sweden, and growth data in the UK.
Asia
The week commenced with Australian housing data released on Sunday, indicating an increase in home sales and auction clearance rates. This development raises expectations for a potential recovery in a property market that has experienced a downturn due to rising interest rates this year. On Monday, inflation updates from China are expected to indicate a slight deceleration in consumer price increases for October, projected at 0.8%, as sectors beyond energy and AI continue to exhibit sluggishness. Factory-gate inflation is projected to rise to 5.4%, marking the quickest rate of increase since June 2022, propelled by supply-side reflationary pressures. Japan is set to release producer prices for October, which are expected to indicate that cost pressures continue to be high. Meanwhile, consumer-price data from India may reveal inflation exceeding 6% for the first time since August 2023. Third-quarter data from the Philippines are anticipated to show a slight acceleration in economic growth. Australia is set to unveil indicators for consumer and business sentiment on Wednesday, with the NAB Business Confidence reading for October anticipated to reflect a negative trend for the ninth consecutive month.
New Zealand’s manufacturing PMI for October is set to be released on Friday, with the index remaining consistently in expansionary territory since July 2025. September household spending data in Japan, set to be released on Tuesday, is anticipated to indicate a decline for the 10th consecutive month. This trend raises questions regarding the Bank of Japan’s claim that a virtuous cycle of increasing incomes will progressively enhance consumer spending. Trade data are forthcoming from China, India, and Taiwan. In the upcoming week, Asia will not witness any central bank decisions; however, the Bank of Japan is set to publish a summary of opinions from its October board meeting. It maintained its settings, while asserting that underlying inflation had ultimately achieved the 2% inflation target. That assessment paves the way for a potential rate hike as early as December.
Europe, Middle East, Africa
Third-quarter UK data on Thursday will demonstrate the strong growth environment leading to the first rate hike since 2023. Expansion is anticipated to have accelerated to 0.7%, marking the most robust growth rate in over two years. Policymaker appearances will undoubtedly attract scrutiny. BOE Governor Andrew Bailey is scheduled to be in Zurich on Monday, while Deputy Governor Clare Lombardelli will address the “Bank of England and Its Watchers” conference the subsequent day. Philip Lane, the chief economist of the European Central Bank, is also scheduled to speak at that event. Meanwhile, after the conclusion of nominations for the ECB presidency, euro-zone finance ministers are set to deliberate on the contest to replace Christine Lagarde during a meeting in Brussels on Monday. Data in the region encompass German exports scheduled for Monday, Italian industrial production set for Wednesday, and a second reading of euro-area GDP anticipated on Friday.
In the Nordics, Sweden’s Riksbank is set to release the minutes of its recent decision to increase borrowing costs on Tuesday. The same day, Norway’s inflation reading is scheduled for release. Egyptian officials will monitor their inflation reading on Tuesday, following a period of two consecutive months of easing price growth. The central bank raised rates unexpectedly in October. Ghana’s finance minister, Cassiel Ato Forson, is set to present his 2027 budget to lawmakers on Thursday, where he is anticipated to detail a $10 billion economic plan designed to stimulate growth and generate employment following years of fiscal consolidation post-default. Russia’s economy is expected to demonstrate modest growth when third-quarter data are released on Friday, as indicated by source. Inflation figures for October, set to be released on Friday, could indicate that annual price growth has surged past 7% for the first time in a year.
Latin America
In Mexico, the upcoming full-month and late-month inflation data scheduled for release on Monday are expected to exceed Banxico’s 3% target, approaching the 4% ceiling. The consensus anticipates readings slightly below the central bank’s revised fourth-quarter forecasts, which were presented alongside its unexpected quarter-point rate cut to 6.25% on November 5. Colombia’s consumer-price report arrives shortly after a rate-setting meeting, during which BanRep’s board decided to maintain the policy rate at a notably restrictive 12.25%. On Tuesday, the focus is on Banco Central do Brasil, as observers of Brazil anticipate insights from the minutes of its meeting held on November 3-4. Few policy meetings have witnessed such a significant alteration in perspective – transitioning from a robust agreement for a sixth consecutive reduction to 13.5%, to the eventual resolution to maintain the key Selic rate at 13.75%. President Luiz Inácio Lula da Silva’s unexpected reelection and his lack of communication regarding strategies for restoring fiscal stability have temporarily marginalised the central bank.
Before the bank’s decision on November 4, local analysts had revised their key rate projections extending to the 2029 forecast horizon. In a timely follow-up, Brazil’s October inflation figures are expected to indicate a further increase from September’s above-target 4.58% reading, aligning with analysts’ latest 2026 forecast of 5.22%. Analysts in Argentina anticipate a third consecutive monthly inflation figure below 2% for October, which may be slower than the 1.9% recorded in September, thereby maintaining the annual inflation rate close to the 33.4% level observed in September. With less than a year remaining until the upcoming election, Argentina finds itself in a technical recession, presenting a significant challenge for President Javier Milei in managing consumer price stability. Peru’s central bank convenes on Thursday, and following 13 consecutive months of maintaining the key rate at 4.25%, Governor Julio Velarde and his team are expected to implement their first increase since January 2023, prompted by an October inflation surge to 5.25%.