Rich Nations Urged to Address Rising Global Debt by IMF Chief
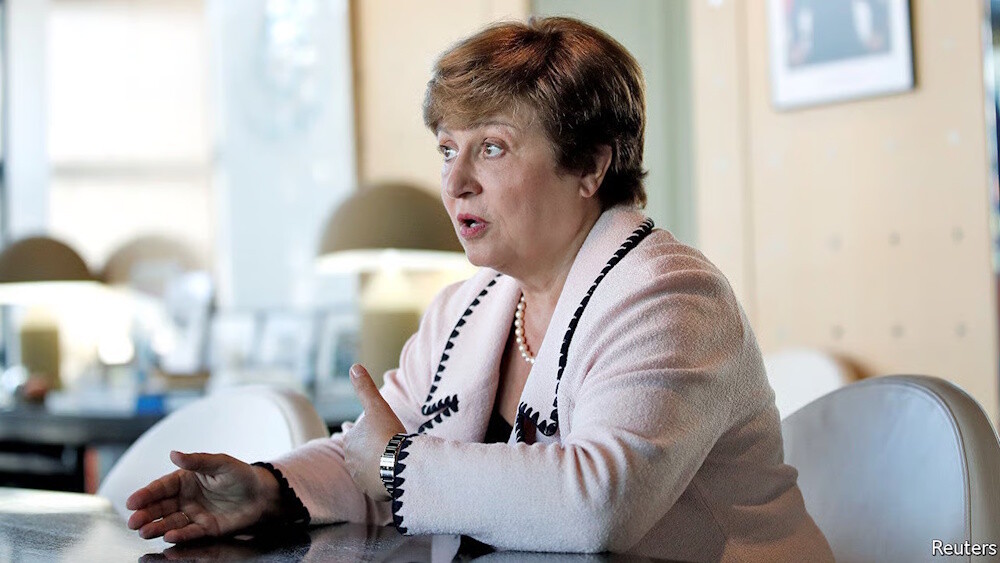
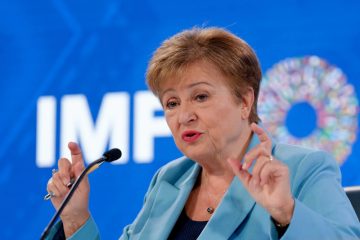
The head of the International Monetary Fund stated on Wednesday that the United States and other affluent nations must urgently address the escalating global debt levels that are disproportionately affecting low-income countries and placing significant pressure on the global financial system. IMF Managing Director Kristalina Georgieva remarked that although US Treasury Secretary Scott Bessent and other US officials acknowledge the excessive growth of the federal deficit and national debt, merely attempting to stimulate the US economy to overcome its national debt exceeding USD 40 trillion will not be adequate. “At the fund, we believe that, growth, of course, helps, but it cannot deliver fast enough the necessary adjustments,” Georgieva said at the autumn meeting of the IMF and World Bank in Bangkok. “There is no magic,” she said, noting some other measures would be needed. “You have to go in a direction of tightening that, bringing it down, bringing deficit down.”
Rising debt levels and global inflation, partly stemming from elevated energy costs linked to the Iran war, have driven interest rates to multidecade highs, exacerbating the challenges faced by the world’s poorest nations. Efforts to manage debt levels through what Georgieva and other experts refer to as “fiscal consolidation” have encountered obstacles due to significant expenditures during the COVID-19 pandemic and the subsequent period. “Fiscal risks are rising, and a proper reaction is largely absent in many countries,” said Rodrigo Valdes. “And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world.” And “Among the world’s poorest countries, interest payments have reached historic highs relative to revenue, and declining amounts of aid are creating gaps that some countries have been unable to finance,” the IMF’s latest Fiscal Monitor said.
That situation compels nations to confront difficult decisions regarding the support of their most vulnerable populations versus fulfilling their debt repayment commitments. “We know that today the median developing country is going to pay, is actually today paying three times more on their interest repayments than developed countries,” Alexander De Croo said in an interview. On average, nearly 10 percent of government spending is allocated to debt repayment. The interplay of elevated prices for fuel, fertiliser, and other essentials, alongside the repercussions of the El Nino weather phenomenon and increased borrowing costs, has constrained the recovery prospects for many low-income countries. “I mean, we don’t see really a light at the end of the tunnel,” De Croo said. Creating employment opportunities, particularly in an era where the rising adoption of artificial intelligence poses a risk to the viability of numerous conventional jobs, remains a critical focus.
Over 1.2 billion young individuals are anticipated to join the global labour market in the forthcoming decade, whereas projections indicate a net addition of merely 400 million new positions. The UNDP announced this week a “Jobs for Prosperity” initiative that will collaborate with governments, development banks, including the World Bank, and private enterprises to stimulate investment in critical job-creating sectors such as tourism, healthcare, and food processing. The initiative and other efforts will concentrate on assisting countries in attracting investment through enhancements in governance and policy frameworks, while simultaneously establishing pipelines of “investible projects,” as stated by De Croo. “These are things that are feasible. It’s been proven that you can do it in many places of the world.”