Central Banks Brace for Critical Week Amid Rising Inflation Risks
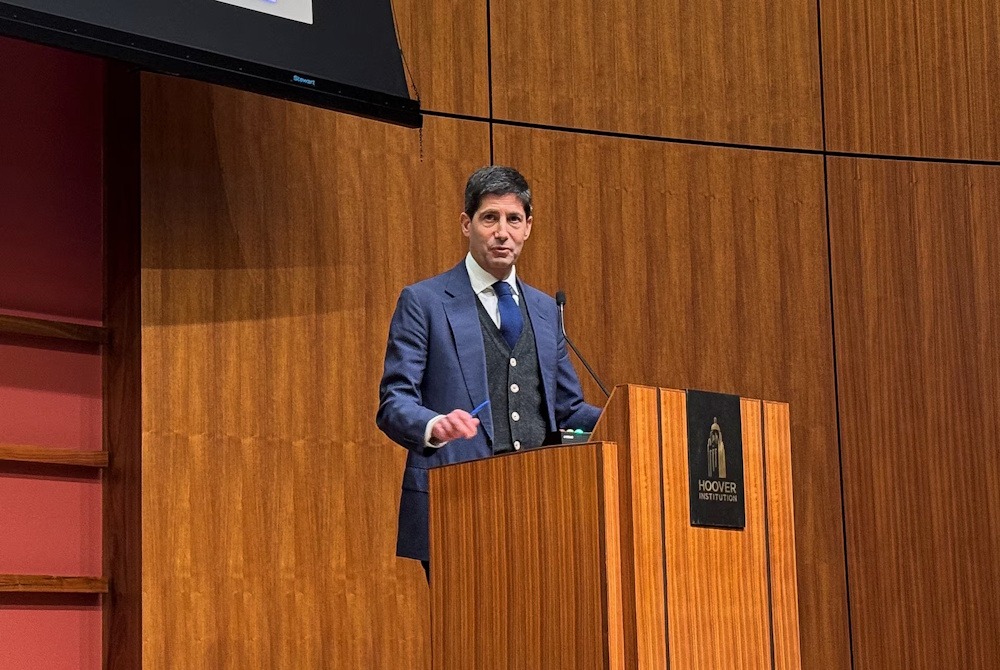
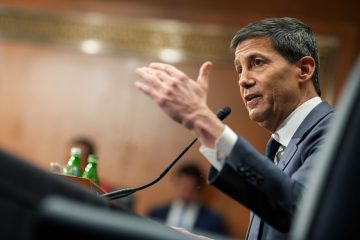
Central banks from a significant portion of the Group of Seven are confronted with a crucial week, as escalating inflation risks intensify the pressure to increase interest rates. Three decisions, commencing with the Federal Reserve on Wednesday and subsequently followed by counterparts in the UK and Japan on consecutive days, have the potential to reshape the global monetary policy framework for the remainder of 2026 and into the future. The US will be under significant scrutiny following a core inflation reading that exceeded expectations on Friday. That fuelled investor expectations that Fed Chairman Kevin Warsh and his colleagues will increase their benchmark rate, likely in opposition to President Donald Trump’s preferences. A Bank of England rate increase on Thursday isn’t anticipated; however, with three officials having favoured such a move at the late-July meeting and with price risks simmering, the possibility of shifting toward a hike as soon as November cannot be ruled out. The Bank of Japan is widely anticipated to increase its key rate at the end of the week, following a series of encouraging data points, including the largest increase in wages the nation has seen in nearly three decades.
With oil emphatically above $100 a barrel again and the West Asia war apparently reigniting, any hope among policymakers for a respite in global price pressures seems faint for now. Following the European Central Bank’s tightening on Thursday, marking the second such action since the onset of the Iran conflict, investors are likely to conclude the week with a clearer view of a progressively synchronised hawkish policy stance among the G7. The club’s other institution, the Bank of Canada, is also progressing in that direction. Minutes from the recent decision, in which officials opted to maintain steady rates while highlighting inflation concerns, are set to be released on Wednesday. In other regions, the focus will be on Chinese industrial data, inflation statistics from the UK, Canada, India, and Japan, along with a likely interest rate reduction in Brazil.
US and Canada
Warsh indicated last month that the Federal Reserve would “have work to do” if it could not “be confident that underlying inflation is moving to our objective, clearly and at sufficient speed.” Friday’s inflation data provided no such reassurance. Investors and economists now regard it as highly probable that the US central bank will increase interest rates for the first time in three years. Support for such a move had been gaining traction at the Fed, even prior to the most recent figures. In July, three officials expressed dissent regarding the decision to maintain steady rates, advocating instead for an increase. On Wednesday, policymakers will unveil revised forecasts concerning economic growth, inflation, and the trajectory of interest rates. The week’s US data docket includes retail sales, which are anticipated to rebound in August, alongside new figures on housing starts and industrial production. In Canada, the August inflation data released on Monday will provide further insights into the economic landscape as the country navigates a tumultuous third quarter, characterised by the intensifying tariff conflict with the United States.
Asia
The primary emphasis for the week will be on China’s August data release scheduled for Tuesday, which is expected to offer the most thorough official insight into the economic developments that occurred in the country during the previous month. Forecasts indicate that there is little expectation among economists for a significant rebound from July, a month during which the economy experienced a widespread slowdown. As has been the case all year, Chinese production and exports of AI-related tech products have expanded rapidly; however, the remainder of the economy is experiencing a downturn. India’s August inflation data, set to be released on Monday, will be closely monitored to assess whether price pressures are becoming more widespread, potentially providing insights into the timing of any rate increases by the RBI. On the same day, the Pakistan central bank is set to announce its rate decision, with analysts anticipating a maintenance of the current rate. The BOJ’s anticipated increase on Friday would mark its second adjustment of the year.
That would elevate the policy rate to 1.25 percent, marking the highest level since 1995, potentially offering additional support to the yen, which has appreciated in recent weeks. The same morning, the government will report national consumer price data for August, with inflation forecast to have risen 2 percent from a year earlier. India, Japan, and New Zealand are set to release their trade data for August in the upcoming week. Notably, Japan’s imports and exports are anticipated to maintain the robust growth trajectory observed throughout the year, with the data scheduled for release on Wednesday. New Zealand on Thursday reports second-quarter gross domestic product growth, with the economy anticipated to have expanded at a slower pace than in the first quarter. That will be the final GDP release prior to the national election in November, and it may influence voters as they determine whether to re-elect Prime Minister Christopher Luxon. Sri Lanka is scheduled to release its GDP figures on Tuesday.
Europe, West Asia, Africa
The upcoming releases from the UK are expected to provide policymakers with insights into the robustness of price pressures ahead of their rate decision later this week. Jobs numbers on Tuesday are anticipated to indicate approximately steady wage growth, whereas the subsequent day, headline inflation is expected to have accelerated in August to 3.1 percent, marking a five-month peak. In addition to the implications for interest rates, the Bank of England meeting will be closely scrutinised for its annual disclosure regarding the pace at which it intends to reduce its bond holdings. In the euro zone, following Thursday’s rate hike, important indicators to watch include industrial production and the ECB’s wage tracker, both scheduled for release on Wednesday. The measure of consumer-price expectations is set to be released on Friday.
ECB chief economist Philip Lane is set to speak at a two-day research conference commencing on Wednesday. Meanwhile, President Christine Lagarde and her colleagues will convene in Dublin for informal discussions with EU finance ministers later in the week. Swedish unemployment metrics are set to be released on Wednesday and Thursday. On the latter day, the Swiss government will release its latest economic forecast as well. Recent data indicated a significant increase in inflation. Further afield, Israel is set to release inflation figures on Tuesday, with a modest acceleration anticipated to 1.6 percent from the previous 1.55 percent. Since that remains within the central bank’s range, it could bolster the argument for renewed rate cuts, although price growth is anticipated to accelerate as the year concludes.
Latin America
In Peru, the initial assessment of third-quarter economic activity on Tuesday is expected to reveal July GDP-proxy figures that align with those of June, as the El Niño weather phenomenon persists in causing supply disruptions. Peru’s economy demonstrated a marginally stronger performance in the second quarter than anticipated, even in light of lacklustre figures recorded in June. In conjunction with the monthly economic activity indicator, the jobs report for the capital city for August is also anticipated. The unemployment rate in Lima reached a historic low of 4.7 percent in July. Brazilian retail sales figures and July economic activity data provide a critical context for the central bank’s rate decision on Wednesday. Analysts and traders anticipate that policymakers, under the leadership of Governor Gabriel Galipolo, will implement a fifth consecutive quarter-point reduction in rates, bringing the Selic down to 13.75 percent. Tight monetary policy, combined with exhausted households, positions Latin America’s leading economy for a third consecutive year of decelerating growth.
However, persistent inflation above target and entrenched expectations are expected to constrain policymakers’ options. In Chile, the minutes from the central bank’s September meeting, which marked a sixth consecutive hold at 4.5 percent, are expected to maintain the cautious and contingent perspective articulated in the post-decision statement. The institution has revised its 2026 GDP estimate downward to a range of 0.25 percent to 0.75 percent, a decrease from the previous forecast of 1 percent to 1.75 percent. The second-quarter output report for Argentina is expected to indicate that South America’s No. 2 economy is struggling, with growth appearing uneven and primarily concentrated in the agriculture, energy, and mining sectors. GDP-proxy data through June suggests a quarter-on-quarter contraction nearing 1 percent, indicating a significant decline from the first quarter’s year-on-year growth rate of 2.3 percent.