Mortgage Rates Cross 7% as Borrowing Costs Keep Rising
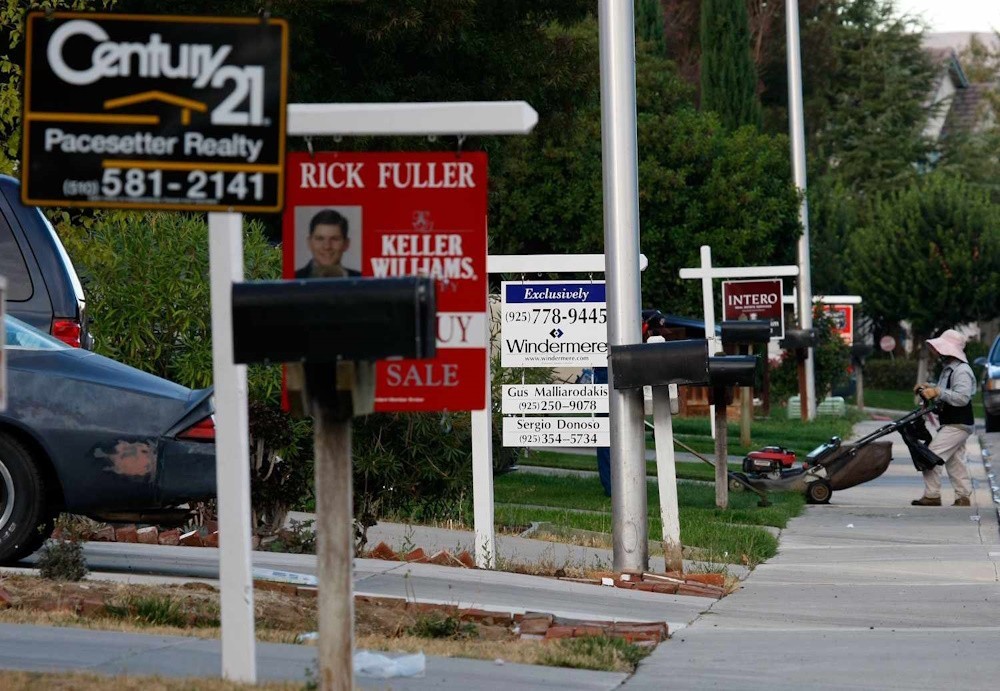
Mortgage rates have ascended to a notable threshold this week, surpassing 7% for the first time since January 2025 and achieving their peak level during either of Donald Trump’s presidential terms. The average 30-year fixed mortgage rate increased to 7.03% this week, rising from 6.95% the previous week, as reported by Freddie Mac on Thursday. For the fifth consecutive week, mortgage rates have continued to rise, further constraining housing affordability. Increased interest rates result in elevated monthly payments and diminished purchasing power for consumers. “Beyond the immediate financial constraints, the 7% threshold is a foreboding psychological barrier,” said Lisa Sturtevant. “Crossing this mark could create a chilling effect on the market, leading to home sales transactions to slow considerably this fall.” However, mortgage rates remain significantly lower than the 7.79% peak observed in 2023, a period characterised by inflation reaching levels not seen in decades. Approximately seven months prior, the average 30-year mortgage rate experienced a temporary decline below 6% for the first time in several years, igniting optimism that reduced borrowing costs would ultimately revitalise the housing market. Instead, those hopes have diminished as the conflict in Iran has driven oil prices upward, exerting additional pressure on overall inflation and mortgage rates.
Consider the distinction between a homebuyer who secured their mortgage rate in February, when the average momentarily dipped to 5.98%, and an individual purchasing today. For a median-priced home with a 20% down payment, the current buyer faces the prospect of paying significantly more in interest over the duration of a 30-year mortgage, amounting to hundreds of thousands of dollars. “Expect 7% as the new normal,” said Lawrence Yun. Activity in the bond market is the primary driver of increased mortgage rates. US bond yields have increased this year, resulting in higher interest rates throughout the economy. The 10-year US Treasury yield serves as a benchmark for mortgage rates: They are loosely correlated with the 10-year yield, which fluctuates in response to investors’ expectations regarding Federal Reserve rate decisions, as well as inflation and growth projections. As the 10-year yield has increased this year, mortgage rates have also risen. This week, the 10-year Treasury yield reached its highest level in nearly two decades, following new data released on Wednesday that indicated a robust economy and heightened concerns regarding inflation. The 10-year yield commenced the year at approximately 4.15% and is currently trading near 5.15%, marking its highest level since 2007. The average 30-year fixed mortgage rate stood at 6.16% at the beginning of the year.
Bond yields are increasing as markets respond to central banks initiating interest rate hikes to mitigate inflation, which has been significantly influenced by the energy shock resulting from the Iran war. The increase in bond yields elevates borrowing costs, prompting concerns among some economists that these yields may have attained levels that could threaten the overall economy. Increased bond yields result in elevated mortgage rates, alongside rises in auto loans, consumer loans, and commercial loans. When Trump departed from office in January 2021, the 30-year fixed mortgage rate stood at just under 2.8%. A property developer and real estate investor, Trump attributed the subsequent increase in mortgage rates directly to the Federal Reserve. Although mortgage rates do not directly align with the central bank’s policy adjustments, Trump frequently criticised former Fed Chair Jerome Powell for not reducing the Fed’s benchmark interest rate swiftly enough when inflation first surged in the early pandemic years. Last week, Trump’s chosen successor to Powell, Kevin Warsh, declared that the central bank increased interest rates by a quarter point – marking its first hike since July 2023 – in a bid to mitigate inflation. The central bank’s members have indicated they anticipate at least one additional rate hike in 2026.
On his social media platform Truth Social, Trump posted last week that “interest rates in the United States should be 1%, or less,” a significant drop from the Fed’s current rate range of 3.75% to 4%. Higher rates are beginning to exert a decelerating effect on the housing market. Shares of some of the country’s largest homebuilders, including Lennar, D.R. Horton, and PulteGroup, have fallen over the past month as higher borrowing costs threaten to weigh on both home sales and new construction. Last week, Lennar CEO Stuart Miller cautioned that numerous homebuyers are “clearly stretching” to secure a home recently, linking the company’s lacklustre earnings to elevated mortgage rates and persistent inflation. Despite the pace of home sales remaining largely unchanged this year relative to last, data from NAR through August indicates that elevated mortgage rates may be deterring some buyers. Pending home sales, which indicate the volume of homes under contract, experienced a 0.3% increase in August compared to July; however, they declined by 4.7% relative to the same period last year, as reported by the National Association of Realtors.
Mortgage applications for purchasing new homes decreased by 11% last week compared to the same week in the previous year, as reported by the Mortgage Bankers Association on Wednesday. Among those still seeking to purchase, an increasing number of borrowers are opting for adjustable-rate mortgages, or ARMs – a more precarious loan product that contributed to the housing market’s escalation leading up to the 2008 financial crisis. According to the MBA, nearly 10% of borrowers chose an ARM last week. These loans generally provide a lower fixed rate for a duration of five, seven, or ten years before adjusting to align with market rates. If rates are elevated at the conclusion of the fixed period, borrowers may encounter significantly increased monthly payments. Rates on 5/1 ARMs, which maintain a fixed rate for the initial five years before transitioning to annual adjustments, were observed to be over a percentage point lower than those associated with fixed-rate loans last week, according to Mike Fratantoni. Home prices have not yet adjusted to indicate a national deceleration in demand, however. The median existing home price reached $429,100 in August, marking the 38th consecutive month of year-over-year price increases, as reported by NAR.